What’s in the blog?
Direct mutual funds have a lower expense ratio, but does that automatically make them the right choice for every investor? This blog explores the difference between direct and regular plans, what the additional cost of a regular plan pays for, and what investor behaviour data tells us about the two. It also helps you evaluate which option suits your financial planning approach, investment discipline and need for ongoing guidance.
Table of Contents
“ If I have the option to invest directly, why should I be paying extra?”
Questions like these were relatively uncommon when I first started my career. Today, with greater access to financial information and growing awareness among investors, more people are questioning the costs they incur and the decisions they make with their money.
And honestly, that’s a very healthy development for the industry. Investors should understand what they are paying for and, more importantly, the value they receive in return.
The recent development mandating direct plans as the default option on AMC digital platforms from November 1, 2026, is likely to bring this question into sharper focus.
I often have this conversation with clients who want to understand the reasoning behind every financial decision. And I believe it’s an important one to have.
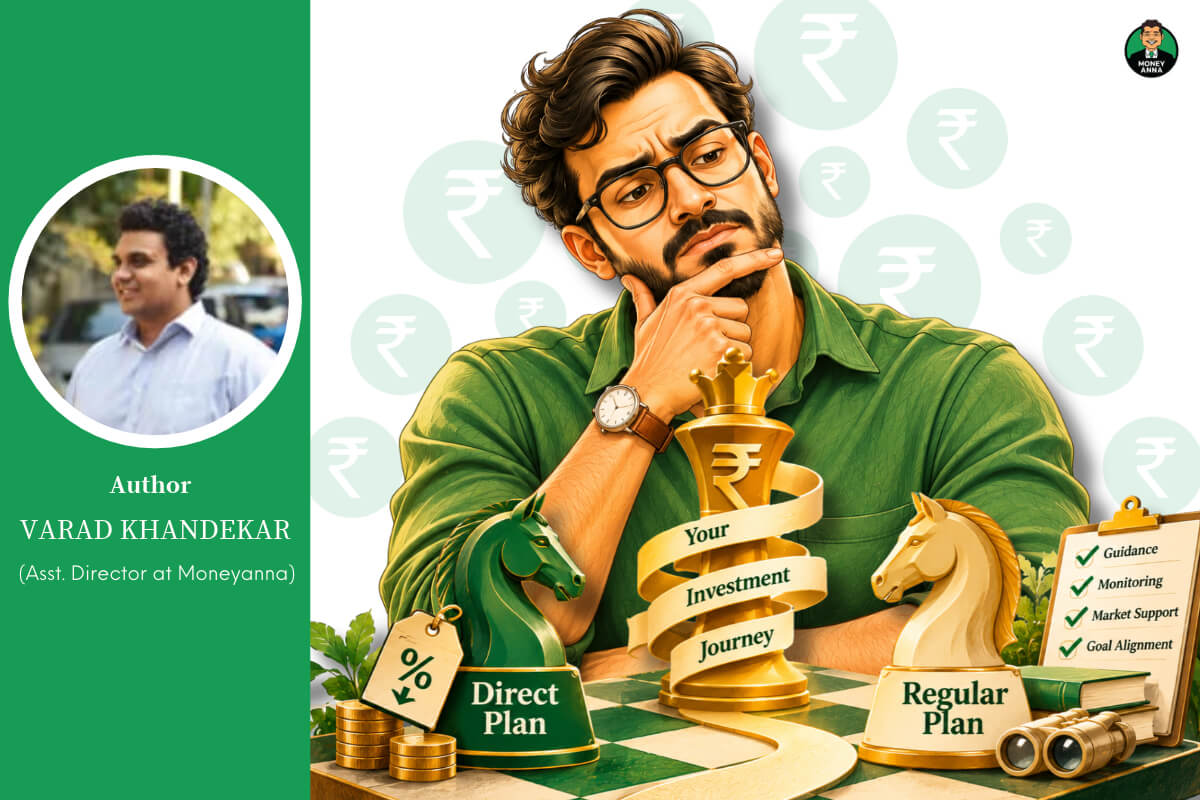
So, rather than simply comparing the expense ratios of direct and regular mutual fund plans, let’s look at the bigger picture. What are you actually choosing between? What role does guidance play in your investment journey? And how do you decide which option makes more sense for you?
Let’s explore.
Understanding Direct and Regular Plans
If you are already asking questions about expense ratios, chances are you are familiar with the basic difference between direct and regular mutual fund plans. If you are, feel free to skip this section.
For the benefit of those who would like a quick refresher, let’s briefly understand the two before we get into some deeper questions. I want to make sure we are on the same page.
Both direct and regular plans are different ways of investing in the same mutual fund scheme. They have the same investment objective, underlying portfolio and fund manager. In other words, if you invest in the direct and regular plans of the same scheme, your money is invested in the same securities.
The difference lies in how you access the scheme and the expenses you pay.
When you invest through a mutual fund distributor, your investment goes into the Regular Plan. Its expense ratio includes distribution-related expenses, including the commission paid to the distributor.
When you invest directly with the AMC, without involving a distributor, you invest in the Direct Plan. Since there are no distributor commissions, the expense ratio is a little lower.
Over time, this difference in expenses can translate into a difference in the returns you earn, even though both plans follow the same investment strategy.
So, yes, from a cost perspective, direct plans have an advantage. There is no denying that.
But is choosing a mutual fund simply about selecting a scheme and paying the lowest possible expense ratio? Or are there other decisions that influence how well your investments serve your financial goals over time?
That’s what we need to explore next.
So, What Are You Paying The Distributor For?
When you choose a regular plan, a part of the expense ratio goes towards compensating the mutual fund distributor. Naturally, this brings us to another question: What exactly does the distributor do to earn this commission?
Is it simply about helping you select a mutual fund, completing the paperwork and getting your investment started? If that were all, one could argue that the additional expense is difficult to justify, especially when investing directly has become so convenient.
But the role of a good mutual fund distributor can extend well beyond helping you make that first investment.
Here are some of the ways a distributor can add value to your investment journey:
- Understanding your investment requirements
Before recommending a scheme, a distributor should understand your investment objectives, time horizon, risk appetite and existing investments. This helps in identifying funds that are more appropriate for your requirements rather than simply chasing recent performers.
- Helping you select and implement investments
With thousands of mutual fund schemes available, selecting suitable funds can be confusing. A distributor helps narrow down the choices, explains the relevant features and assists with the investment process.
- Monitoring your investments
Investing is not a one-time activity. Your portfolio needs periodic attention to identify changes in fund performance, portfolio composition and suitability. A distributor can help you review these aspects and identify when a closer evaluation may be needed.
- Helping you navigate market volatility
This is perhaps one of the most important aspects of ongoing engagement. When markets correct sharply, investors may feel tempted to stop their SIPs, redeem investments or move to funds that have recently performed better. A distributor can help investors evaluate these decisions in the context of their original investment strategy.
- Keeping your investments aligned with changing requirements
Your financial circumstances don’t remain the same throughout life. Your income, liabilities, family responsibilities and financial goals evolve. A distributor can help you review your investments when these changes occur and assess whether any adjustments are required.
Of course, the actual services and level of engagement can vary from one distributor to another. A regular plan by itself does not guarantee all these services. It is important to understand what your distributor actually offers and whether you are receiving value for the cost you incur.
The point is that the additional expense should be evaluated against the service and support you receive, not merely viewed as an unnecessary deduction from your returns.
The interesting story told by data
We just discussed how a mutual fund distributor’s role can extend beyond helping you make an investment. But does this ongoing involvement have any observable connection with how investors manage their investments?
An interesting comparison in the AMFI-Crisil Mutual Fund Factbook 2026 offers some food for thought.
As of March 2026, 34.4% of the assets invested through regular-plan SIPs had remained invested for more than five years. For direct-plan SIPs, this figure was 19.9%.
The difference is quite significant.
The pattern is similar when we look at the broader mutual fund industry. Around 23.5% of regular-plan assets had a holding period of more than five years, compared with 14% of direct-plan assets.
There is another interesting observation. Direct plans have a relatively higher share of newer SIP investments. Around 29% of direct-plan SIP assets were less than a year old, compared with approximately 19% for regular plans.
Does this mean investors choosing regular plans are necessarily more disciplined? Not necessarily. The data does not establish that distributor involvement is the reason behind these differences. Investor profiles, investment preferences, the nature of investments and several other factors could influence the numbers.
However, the pattern does raise an interesting question: Could the availability of ongoing guidance and support be one of the factors helping investors remain committed to their investments over longer periods?
After all, starting an investment is relatively easy today. Staying committed to it through changing market conditions and personal circumstances is a different challenge altogether.
And this is where the value of having someone to guide you through your investment journey deserves consideration.
Direct or Regular: Which one makes more sense for you?
By now, you might be wondering whether direct or regular plans are better suited to your investment journey.
The honest answer is that neither is universally better. It depends on how you manage your investments, the kind of support you need and how closely you stay involved in your financial plan.
Let’s look at a few situations.
Direct plans may make more sense if:
- You understand mutual funds, asset allocation and the risks associated with your investments.
- You are comfortable researching and selecting funds independently.
- You have a well-defined financial plan and review it periodically with a financial planner.
- You can independently execute the recommendations and rebalance your portfolio when required.
- You have the discipline to stay committed to your investment strategy, even during volatile markets.
Regular plans may make more sense if:
- You would rather have someone help you navigate the different mutual fund options available.
- You need assistance with selecting and implementing investments.
- You value having a distributor who understands your investment journey and is available when you need guidance.
- You find it difficult to monitor your investments and evaluate whether changes are required.
- You would benefit from regular engagement and support to stay committed to your investment strategy.
However, choosing a regular plan should not mean blindly delegating every investment decision. You should know what your distributor is doing, what services you receive and how frequently your investments are reviewed.
Ultimately, the choice should come down to the kind of support you need and the value you receive from it. Paying an additional expense makes sense only when the associated service adds value to your investment journey.
Before you decide, ask yourself these questions
Before choosing between direct and regular plans, take a moment to answer these questions honestly. The objective isn’t to prove that one option is better than the other. It’s to understand how much involvement and support you need to manage your investments effectively.
- Do I understand my overall asset allocation?
Do I know how much of my portfolio is invested in equity, debt and other asset classes? More importantly, do I understand why that allocation is appropriate for my financial goals and risk appetite?
- Can I independently evaluate and select mutual funds?
Am I comfortable looking beyond recent returns and evaluating a fund based on its investment strategy, portfolio, risk and suitability for my requirements?
- Who reviews my portfolio and when?
Do I have a defined process for reviewing my investments? Am I checking whether my portfolio remains aligned with my goals, or do I only look at it when markets are doing particularly well or badly?
- How do I react when markets become volatile?
When markets fall sharply or a fund goes through a prolonged period of underperformance, can I evaluate the situation objectively? Or am I likely to make decisions based on fear, recent performance or what everyone around me is doing?
- Who helps me when my financial circumstances change?
A new financial responsibility, a change in income or a shift in retirement plans can alter the way you need to invest. Do I have someone who helps me assess the impact of these changes on my existing investments?
- Do I have someone who helps me translate my financial plan into action?
Preparing a financial plan is one part of the journey. Implementing it, reviewing it and making necessary adjustments are equally important. Am I equipped to manage this process independently, or would I benefit from ongoing professional support?
If you have the knowledge, discipline and time to manage these responsibilities, direct plans could be a suitable choice. And if you already work with an independent financial planner who reviews your investments regularly, you may be able to combine that professional guidance with direct-plan investments.
On the other hand, if you value having a distributor who helps you select, implement and monitor your mutual fund investments, regular plans may be worth considering.
The important thing is to make this choice consciously, with a clear understanding of both the cost and the value you receive.
The MoneyAnna Promise: Guidance Beyond Transactions.
At the end of the day, choosing between direct and regular plans shouldn’t be about following what is presented as the default option or simply choosing the one with the lower expense ratio.
It should be about understanding your own requirements and making sure you have the right support system to manage your investments.
At MoneyAnna, we believe investors should know what they are paying for and why. As a mutual fund distributor, our responsibility goes beyond helping you complete an investment transaction. We want to understand your financial requirements, help you make informed investment decisions and stay connected through the different phases of your investment journey.
We also believe that every investor should have the freedom to ask questions, understand the costs involved and make choices that suit their circumstances. If direct plans are right for your situation, you should be able to make that choice with confidence. If you need the guidance and ongoing support that comes with a regular-plan relationship, you should know exactly what value you are receiving.
Because ultimately, our job isn’t to convince you to choose a particular plan. It’s to help you make financial decisions that you understand, feel confident about and can stay committed to.
And that’s what we believe a good financial relationship should look like.
Frequently asked questions (FAQ)
The choice of direct vs. regular mutual funds depends on how independently you can manage your investments and the kind of support you need. If you understand fund selection, asset allocation and portfolio reviews, direct plans may suit you. If you value ongoing assistance with investment selection, implementation and monitoring, regular plans may be worth considering.
No. Direct plans have a lower expense ratio, which gives them a cost advantage. However, the right choice also depends on your investment knowledge, discipline and access to professional guidance. A lower expense ratio alone does not guarantee better investment decisions or outcomes.
Yes. You can work with an independent financial planner for your financial plan, portfolio reviews and investment guidance while executing your mutual fund investments through direct plans. The important thing is to have clarity on the services being provided and the associated fees.
Yes. You can generally switch from a regular plan to its corresponding direct plan without withdrawing the money to your bank account. However, such a switch is treated as a redemption from the regular plan and a fresh purchase in the direct plan. It may attract applicable capital gains tax and exit load, if any. Evaluate these implications before making the switch.
A mutual fund distributor may assist with understanding investment requirements, selecting suitable schemes, completing transactions, monitoring investments and providing ongoing investment-related support. However, the actual services can vary between distributors. Investors should understand the scope and frequency of support they will receive. With MoneyAnna you get end-to-end handholding and support.